

CoverMe - Instant Cash Advance
by DIONIS K
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
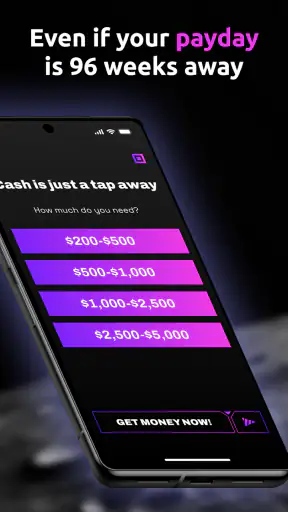
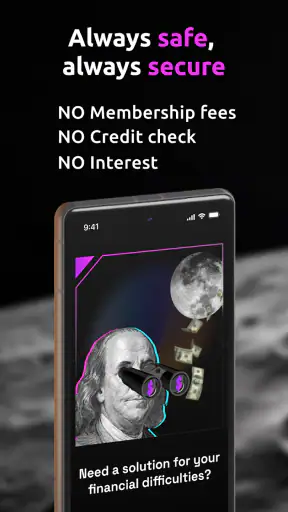
 Analysis by Getfullapps
When an unexpected bill lands before payday, the appeal of CoverMe - Instant Cash Advance is easy to understand. I looked at it as a finance app for short-term cash needs rather than as a general budgeting tool, and that distinction matters. Its central promise is built around helping you access money even when your next payday is still far away, which makes it more relevant to an urgent expense than to everyday money management.
The app is free to download, carries an Everyone age rating, and is developed by DIONIS K. It has reached over 100 thousand installs, with a 4.6 average from around 32 thousand ratings and roughly 2 thousand reviews. Those figures suggest that many people find the basic idea useful, but they do not remove the need to examine how well it fits into a longer-term financial routine. A cash advance can solve a timing problem; it does not automatically solve an income problem.
How CoverMe feels after the first week
During the first week, the strongest part of the experience is the directness of its purpose. I do not open it expecting charts, investment tools, or a full personal-finance dashboard. I open it because I want to understand whether it can help me bridge a gap between an expense and the money I expect to receive later. That narrow focus makes the app easier to judge than a crowded finance platform with many unrelated sections.
A realistic example would be a necessary household purchase that cannot reasonably wait until payday. In that situation, I would first write down the exact amount needed, the date the expense must be paid, and the date I expect to have replacement money available. Only then would I use CoverMe to explore the advance. This order is important: the app should support a decision I have already thought through, not encourage me to borrow simply because the option is visible.
The store summary positions the service as an alternative to typical cash advances, especially for someone whose payday is many weeks away. I see the practical appeal, but I would treat that wording as a reason to compare the complete repayment obligation rather than as proof that the choice is automatically cheaper or safer. The useful question is not only “Can I get cash?” but also “What will this decision do to my next several weeks?”
One of my first recommendations is to keep the requested amount as close as possible to the actual shortfall. Borrowing extra for convenience can turn a small timing issue into a larger repayment problem. This is one of the less obvious habits that makes an app like this more useful: decide the amount offline, then use the app to check whether the proposed advance fits the plan.
I would also read every screen carefully before accepting anything. A finance app can feel simple while still presenting important details through eligibility steps, repayment information, or confirmation pages. I would not rush through those screens just because the need feels urgent. If a term, fee, repayment date, or requirement is unclear, that is a good reason to pause and seek clarification before proceeding.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The first-week experience is therefore strongest for someone with a specific, temporary cash-flow gap. It is less convincing for someone who needs recurring help with rent, food, utilities, or debt payments. Repeated advances may make the immediate week easier while leaving the following month tighter. CoverMe can be a tool for timing; it should not become a substitute for a sustainable spending plan.
What I would check before accepting an advance
I would make a small checklist before using the service. First, I would identify the expense and separate necessities from optional purchases. Second, I would confirm when the repayment will affect my available money. Third, I would leave room for ordinary expenses that arrive before that repayment. Finally, I would ask whether another route, such as delaying a purchase, negotiating a bill date, using savings, or contacting the biller, would create less pressure.
This workflow may sound cautious, but it is exactly where an instant-cash app needs personal discipline. Speed is useful when a bill is time-sensitive, yet speed also reduces the time available for comparison. My practical tip is to take a screenshot or note of the final terms for your own records before confirming. That gives you something concrete to revisit when planning the rest of the month.
Another useful distinction is between eligibility and affordability. Even if the app presents an advance as available, that does not mean the repayment is comfortable. I would calculate the remaining money after the expected repayment, not merely look at whether the advance covers today’s expense. This simple check is more valuable than focusing on the amount that can be accessed.
Where it stands beside familiar alternatives
Compared with a traditional bank overdraft or a credit card, CoverMe may feel more focused on the immediate gap between today and future income. A bank product may be more familiar and could be preferable for someone who already understands its terms and has a stable repayment plan. A credit card can offer flexibility, but it may also encourage a balance to remain open longer than intended. The better option depends on the full cost, timing, and repayment behavior, not on the speed of the application alone.
Compared with borrowing from a friend or family member, an app offers a more private route and avoids an uncomfortable personal conversation. The trade-off is that a personal loan may be more flexible about timing, while an app-based advance is governed by its own process and conditions. Compared with a budgeting app, CoverMe addresses liquidity rather than prevention: it may help with a shortfall, but it will not replace the value of tracking recurring expenses and building a buffer.
That comparison leads to a clear first-week conclusion. I would recommend trying it only when the need is defined, the repayment path is realistic, and I have checked alternatives. I would not install it merely because the idea of available cash feels reassuring. The app’s value comes from solving a particular timing problem, not from being permanently available in the background.
Whether it earns a place from month to month
After the novelty fades, a finance app has to justify repeated attention. In my view, CoverMe’s recurring value depends almost entirely on whether my financial life occasionally produces short, predictable gaps. If those gaps are rare, I would rather keep the app as an emergency option and avoid making advances part of my normal monthly routine. If they happen often, the frequency itself is a warning that the underlying budget needs attention.
The app is not the kind of product I would open every morning. Its role is event-based: an expense appears, I review the situation, and I decide whether a cash advance is appropriate. That can be a strength because it avoids unnecessary daily engagement. It can also be a weakness if a user expects ongoing guidance, spending analysis, savings goals, or a broader view of financial health.
For month-to-month use, I would keep a simple record outside the app. I would note the date of any advance, the amount received, the total repayment obligation, and the effect on the next pay cycle. This is a concrete way to prevent separate short-term decisions from blending together. It also makes it easier to see whether the service is genuinely helping or merely moving the same shortage forward.
A second long-term tip is to create a personal stop rule. For example, I might decide that I will not take another advance while a previous one is still affecting my budget, or that I will pause after one use and review the cause of the shortfall. The exact rule is personal, but having one matters. Without it, the convenience of a finance app can quietly become a recurring habit.
The app’s current version is 1.6.3, and I would keep it updated through the normal app-store process. Updates can matter more in finance than in casual utility apps because reliability and compatibility are important when money is involved. At the same time, an updated app does not change the need to review each transaction carefully. Software maintenance and financial judgment are separate responsibilities.
For someone paid irregularly, the appeal may be stronger than for someone with a predictable salary. A freelancer, seasonal worker, or person waiting for a delayed payment may face timing issues that do not fit neatly into a standard payday cycle. Even then, I would use the app only when the expected incoming money is reasonably dependable. An uncertain future payment is a weak foundation for any advance.
For someone with stable income but frequent shortages, I would choose a different first step. I would review subscriptions, recurring bills, transport costs, food spending, and debt obligations before relying on CoverMe repeatedly. An advance can be appropriate for an isolated emergency, but it is a poor replacement for fixing a monthly deficit. That is the main boundary I would explain to a friend considering the app.
Who gets the most lasting value
The best fit is a careful adult who occasionally needs to bridge a genuine timing gap and is willing to read the terms before proceeding. The app may also suit someone who values privacy and wants an alternative to asking another person for help. Its focused purpose makes it easier to understand than a large financial platform when the only question is whether a short-term advance could cover a specific need.
I would skip it if I needed investment management, credit-building education, debt counseling, detailed spending categories, or a complete household budget. Those goals require different tools. I would also skip it if I could not identify a dependable repayment source. The app may be free to download, but the financial decision it supports should never be treated as costless simply because installation does not require payment.
The Everyone rating makes the app broadly accessible from an app-store perspective, but I would not interpret that as a recommendation for every financial situation. Younger users and anyone unfamiliar with borrowing should involve a trusted adult or financial adviser before accepting an advance. Accessibility is not the same thing as suitability.
Maintenance, friction, and the reasons users may tire of it
The maintenance burden is not likely to come from daily setup; it comes from staying honest about repayment. Every time I considered using the app, I would need to review the amount, timing, and impact on upcoming expenses. That mental work cannot be automated away. If I stopped checking those details, the service would become more convenient than it was safe for me to use.
One source of fatigue is the possibility of repeating the same decision under pressure. An urgent bill can make any available option look attractive, and the more familiar the app becomes, the easier it may be to skip comparison shopping. I would counter that by keeping alternative actions visible: call the biller, delay the purchase, use an existing emergency fund, or ask whether a payment arrangement is available.
Another source of friction is uncertainty around the full transaction experience. I would want to understand eligibility, timing, repayment, and any applicable costs before making a commitment. If those details are not immediately clear on the relevant screens, I would consider that a meaningful usability problem, not a minor inconvenience. Financial products need plain explanations because users often open them when they are already stressed.
I would also be cautious about notifications and the emotional effect of seeing a cash option when I am not actively looking for one. I would keep my use intentional rather than browsing for available money. The healthiest relationship with this type of app is probably occasional and deliberate. If it starts influencing ordinary purchases, that is a sign to step back.
The developer, DIONIS K, has released a focused finance product rather than a broad money-management suite. That focus is useful, but it also means I would not expect the app alone to provide the structure needed for long-term financial improvement. I would pair it with a separate budget, even if that budget is only a basic note on my phone. The combination is more sensible than asking a cash-advance tool to perform the job of a complete financial planner.
There is also a practical record-keeping issue. I would save confirmation details and monitor my bank balance around the expected repayment period. I would not assume that remembering the transaction is enough, especially if several bills arrive at once. This small habit reduces the risk of treating the advance as forgotten money and helps me notice whether the repayment creates a second shortfall.
The trade-off between speed and deliberation
CoverMe’s core attraction is speed and access when a payday is not close. The trade-off is that a fast decision can hide the longer financial consequence. I would use the app when speed genuinely matters, but I would not let speed determine the amount or the repayment plan. Those decisions deserve the same care I would give any other borrowing choice.
If a different option provides clearer terms, a lower total cost, or a repayment schedule that better matches my income, I would choose that option instead. Familiarity with CoverMe would not be a reason to stay with it. In personal finance, the best tool is the one that leaves the least damaging obligation after the immediate problem has passed.
I would also avoid judging the app solely by its rating. The 4.6 average and large number of ratings show strong user interest and generally positive reception, but individual circumstances differ sharply. Someone who used it successfully for one emergency may have had a very different experience from someone facing repeated income gaps. I would treat public feedback as context, then make the decision based on my own repayment capacity.
My long-term verdict on CoverMe
After looking beyond the first impression, I see CoverMe as a narrowly useful finance app rather than a complete answer to financial stress. Its lasting place on my phone would depend on whether I occasionally face a clear, temporary gap and can repay without disrupting essential spending. In that situation, its focused design and free access make it worth considering.
I would not keep it as a psychological safety net for everyday spending. The most important test is what happens after the cash arrives. If the advance allows me to handle a one-off obligation and return to normal budgeting, it has served a reasonable purpose. If it becomes part of every month’s plan, I would remove it from the center of my strategy and address the recurring shortfall directly.
My strongest recommendation is to use a three-step routine: define the expense, calculate the repayment impact, and compare at least one alternative before accepting anything. I would then record the transaction and review the next pay cycle afterward. Those steps add the judgment that an instant-cash product cannot provide by itself.
CoverMe is worth considering for people who need a private, focused way to explore a short-term cash advance and who understand that convenience does not erase responsibility. It is not the right choice for long-term debt, regular overspending, or anyone seeking a full budgeting and financial-planning system. Its real value lasts only when it remains an occasional bridge, not a permanent part of the road.
With a release date of February 20, 2025, the app is still a relatively recent addition to the finance category, and its current version shows that it is being maintained as a live product. I would keep an eye on how the experience develops, but I would make today’s decision based on the terms and repayment reality in front of me. For a carefully planned emergency, I can see why it appeals to many users; for recurring financial pressure, I would choose a broader solution.
Pros
- Fast application process with clear eligibility information.
- Funds can help cover unexpected expenses between paychecks.
- Repayment details are presented before accepting an advance.
- Useful account tools for tracking advances and payment dates.
- Mobile access makes managing requests convenient while traveling.
Cons
- Approval and advance amounts may vary based on personal financial data.
- Fees or optional charges can make borrowing more expensive.
- Late repayment may affect future eligibility or account access.
- Not available in every state or to all types of applicants.
- Requires sensitive personal and banking information to operate.
FAQs for CoverMe - Instant Cash Advance
What is CoverMe - Instant Cash Advance, and how does it work?
CoverMe - Instant Cash Advance is a financial app designed to help eligible users request access to short-term cash advances through a mobile device. After creating an account, you typically provide personal and financial information, review the available offer, and choose whether to accept it. Approval, advance amounts, fees, repayment terms, and funding speed can vary depending on eligibility and the provider’s policies.
Is CoverMe - Instant Cash Advance a loan, and what costs should I check?
An advance obtained through CoverMe may involve repayment obligations, fees, or other charges, so users should carefully read the offer before accepting it. Do not assume that an advertised advance is free or that every applicant receives the same terms. Check the annual percentage rate where applicable, subscription charges, transfer fees, late-payment consequences, and the total amount you will repay.
Who can use CoverMe, and what information is required to apply?
Eligibility may depend on factors such as your age, location, identity, income, employment details, banking information, and ability to repay. The app may request permission to verify your identity and connect to a bank account or payment method. Requirements can change over time, and installing the app does not guarantee approval, a specific advance amount, or instant funding.
How quickly can money arrive after approval through CoverMe?
Funding speed depends on the application review, your bank, the selected delivery method, weekends or holidays, and whether additional verification is required. Some users may receive funds quickly, while others may experience delays. Before accepting an offer, review the estimated delivery time and any expedited-transfer fee. Make sure the linked bank account is active and able to receive deposits.
Is CoverMe - Instant Cash Advance safe to use, and what should I consider before downloading it?
Before using CoverMe, download it only from an official app store and confirm the developer, privacy policy, user reviews, and requested permissions. Financial apps handle sensitive information, so use a strong password and avoid sharing verification codes. Also review repayment dates and cancellation options carefully. If the terms are unclear, contact official support and avoid accepting an offer until you understand the full cost.











